Volatility picks up across markets, let's see where we stand.
It has been a news heavy week, to say the least. The conflict in Iran remains ongoing with not much clarity into what’s next. While there is a clear push to have US forces there for as little as possible, it’s an extremely fluid situation. Whenever these types of events happen, it’s good practice to take a step back from the news and look through charts to get a better idea where we stand. US equity markets dove lower Sunday evening into Monday morning but were able to retrace the entire move during regular trading hours. The first half of the playbook was run again as equities fell into the open on Tuesday. At the time of this writing, it is yet to be seen if there will be another quick retracement during the day.
Nonetheless, let’s look at the trend chart for the S&P 500 Index (SPX) to see where we stand and areas of interest. The SPX did break a quadruple bottom during Tuesday’s action to mark its first sell signal since November and dropped to its lowest level this year. However, the large cap benchmark has been very choppy over the last few months, so the sell signal is not a major concern unless the bottom of the chop area is taken out around 6550. The SPX is trading well above its bullish support line, so there is not a trend break to keep a close eye on for now. The overall technical picture is still strong, but a break to 6500 or below could spell plenty of trouble with untested support levels sparsely laid out below. After a quick run up in the second half of last year and consolidation this year, this is the primary concern for bulls from a price action standpoint. However, until the bottom of the range at 6550 (or the top at 7000) is taken out, we could still see more chop moving forward before the market chooses the direction for its next big move.

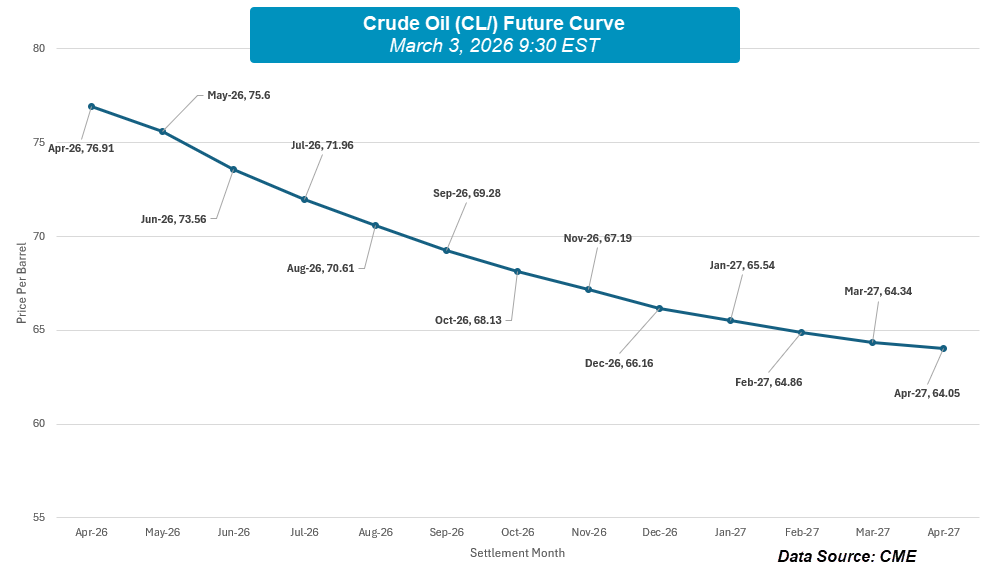
Volatility has perked higher in equity markets, but commodities, particularly Crude Oil (CL/), have had violent moves this week. Crude oil has been showing signs of strength over the last month and change as the chances of conflict in Iran increased. The commodity returned to a positive trend in January and with today’s action tested the highs from 2025 which have acted as resistance so far during the trading day. Anytime there is a shock to the oil market, one of the first places I look at is the forward futures curve for oil. For those unfamiliar, the forward futures curve just shows the price of each futures contract at each settlement date. Normally, the futures contract closest to settlement is cheaper than those further out as there is some uncertainty premium priced into the dates further away from today. However, in times of uncertainty like today, we can see the price for oil in the front month be higher than the price of oil six months from now. This is usually a sign of short-term panic or lack of supply while the expectation is that prices will come back down once the dust begins to settle. With technical resistance holding and the market’s expectation of lower prices in the future, investors should be wary of adding direct oil exposure at this time.